Assumptions of the Cooperative Compliance Programme
Data publikacji: 6/25/2026
Data aktualizacji: 10/5/2026
Unlike a tax audit, the Cooperative Compliance Programme does not constitute direct supervision over the correct fulfilment of tax obligations. It defines the principles of close and constant cooperation between the Taxpayer and the Head of the NRA, based on mutual trust, understanding, and transparency, the aim of which is to ensure the Taxpayer's compliance with tax law regulations with the support provided by the Head of the NRA.
- The objective of the Programme is to undertake joint actions aimed at ensuring compliance with tax law, with particular emphasis on the individual needs and expectations of key taxpayers, in order to provide better conditions for conducting business activity in Poland.
- We operate based on the guidelines of the OECD (The Organisation for Economic Co-operation and Development).
- We provide tailored service adapted to a given taxpayer.
- We adjust the level of cooperation and monitoring of the taxpayer to the control measures they have implemented over internal processes, including supervision over tax matters.
This model of cooperation with taxpayers has already been implemented in several dozen countries, including Australia, Belgium, the Netherlands, Spain, France, and Austria.
Mutual trust (of the NRA in taxpayers and of taxpayers in the NRA) is the justified belief that the partner will act in accordance with the agreed rules.
Mutual transparency is the readiness and ability of the entity applying for or covered by the Programme, as well as the NRA, to be open regarding tax matters. Transparency on the part of the NRA means openness in providing information about the circumstances related to the questions addressed to the taxpayer, as well as in the implementation of cooperation with the taxpayer.
Mutual understanding is the knowledge of both parties' positions and interests. Understanding means that the parties consciously cooperate in a common interest, which is the correct fulfilment of tax obligations.
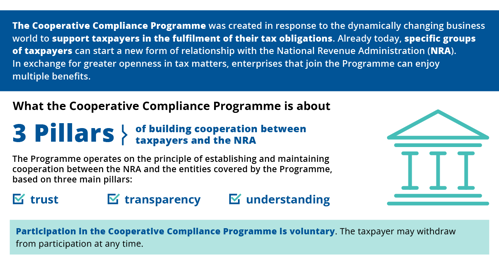
Participation in the Programme is voluntary and initiated by the interested entity. The willingness to participate should be expressed by the taxpayer in writing.
Stages of the Programme
The Cooperative Compliance Programme consists of two essential elements:
- the admission process, the final stage of which is the signing of the cooperation agreement,
- supervision over the taxpayer within the Programme.
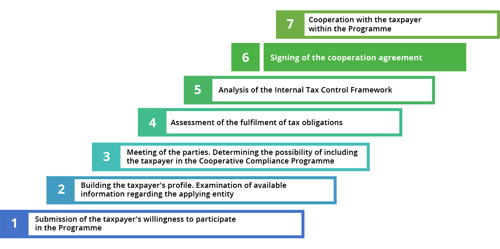
The operational process of the Cooperative Compliance Programme – text version
Stage I:
- Voluntary submission of the taxpayer's willingness to participate.
- Taxpayer profile, i.e. risk assessment.
- A meeting of the parties and assessment of the possibility of inclusion in the Cooperative Compliance Programme.
- Preliminary Audit – assessment of the fulfilment of tax obligations and analysis of the Internal Tax Control Framework (ITCF).
- Analysis of the Internal Tax Control Framework (ITCF).
- Signing of the cooperation agreement.
Stage II:
- Cooperation with the taxpayer within the Programme – monitoring.
Presentations regarding the Cooperative Compliance Programme
- PL_Prezentacja Programu Współdziałania (pptx, 6225 kB)
- EN_Presentation Compliance Cooperation (pptx, 6294 kB)
In case of any questions, the Cooperative Compliance Programme Team will gladly organise a meeting to provide you with detailed information.
Please feel free to contact us at the following email address: program.wspoldzialania@mf.gov.pl